Table of Content
Quick Summary:
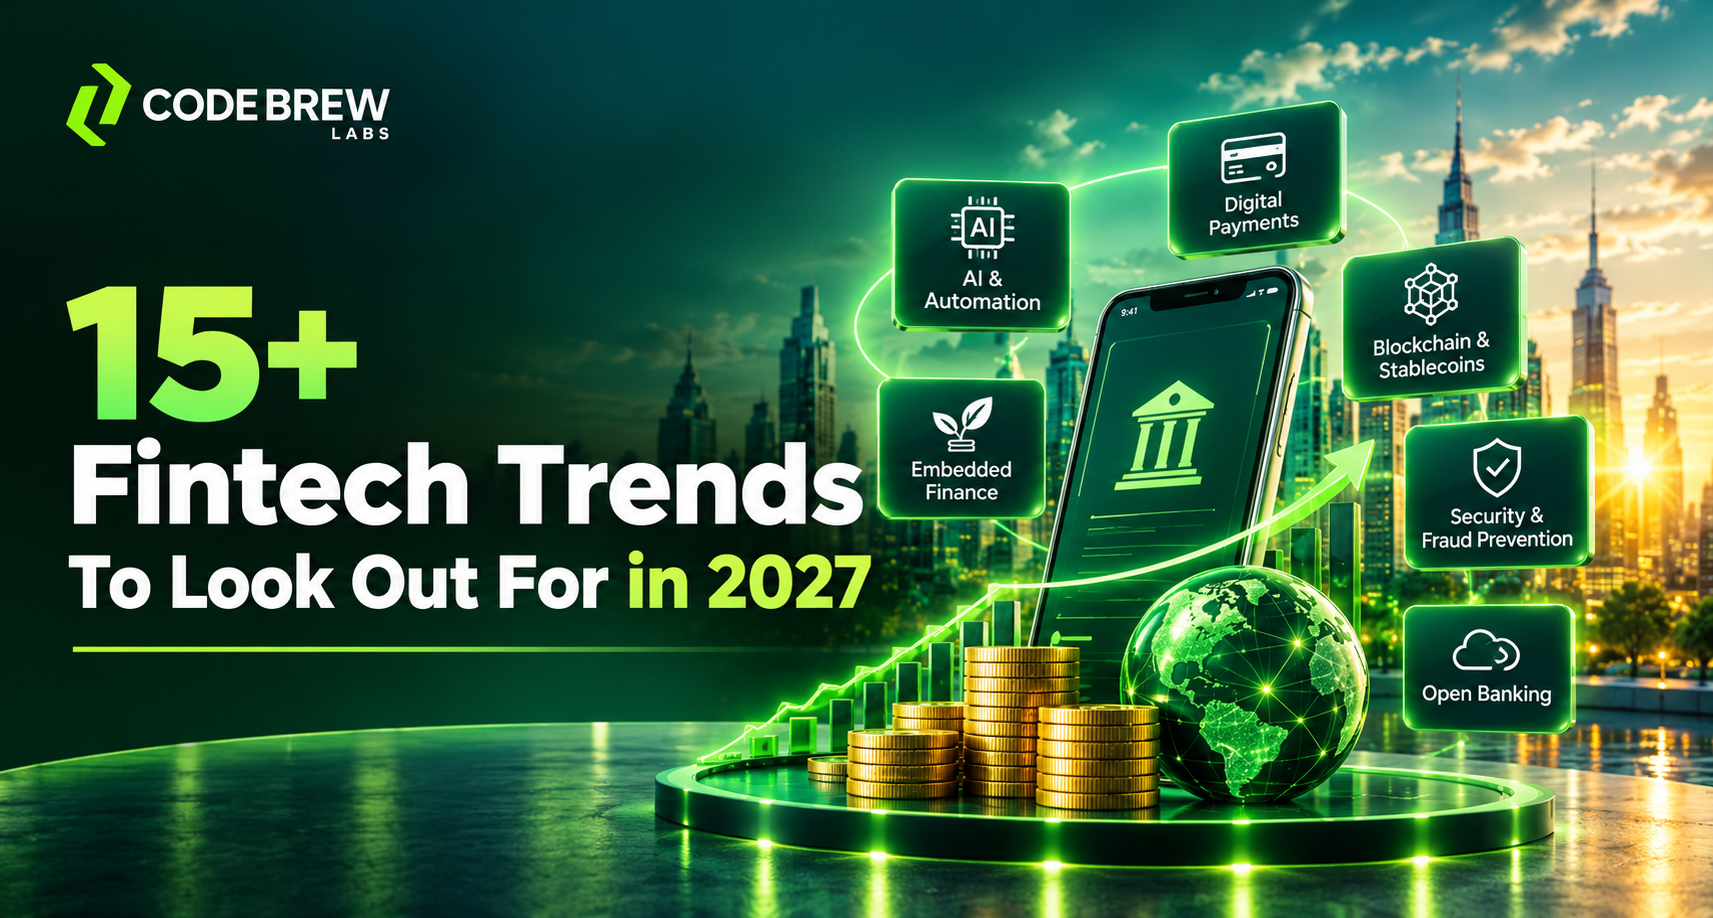
- Fintech trends in 2027 are centered on AI-powered automation, faster payments, digital asset regulation, embedded finance, and stronger financial security.
- Emerging technologies such as AI agents, stablecoins, tokenized deposits, and open banking are reshaping financial services and payment infrastructure.
- Fraud prevention, regulatory technology, data privacy, and secure integrations remain critical to building reliable fintech products.
- Fintech startups must align technology investments with customer needs, business objectives, technical feasibility, and regulatory requirements.
- A focused approach to fintech innovation enables businesses to develop secure, scalable, and customer-centric financial solutions.
Fintech founders have no shortage of new ideas to chase. AI agents promise to take work off employees’ hands, instant payments are changing expectations around money movement, and stablecoins are moving into a more defined regulatory environment. At the same time, fraud is getting harder to spot and the cost of building a secure financial product remains high. The challenge for entrepreneurs is not keeping up with every announcement. It is working out which changes matter to their customers and business model.
Table of Content
The US market will be shaped by technology, customer adoption, and regulation in roughly equal measure in 2027. Some developments are ready for practical use today; others need careful testing or depend on rules and infrastructure that are still evolving.
Key Fintech Trends Shaping the Industry in 2027
The fintech industry is evolving through advances in AI, digital payments, financial infrastructure, and security. The following trends highlight the technologies, opportunities, and challenges shaping the future of financial services.
-
AI Agents Move from Answering Questions to Doing the Work
The first wave of financial-services AI was largely about finding information, summarizing documents, and answering routine questions. AI agents take the next step: they can move through a series of tasks, gather information from approved sources, prepare documents, and hand work to a person for review. In a fintech operation, that might mean assembling a loan file, organizing a dispute, or helping a compliance team review a customer record.
The most useful starting point is usually an unglamorous process that takes staff time every day. An agent that prepares a consistent first draft can be valuable long before a company is ready to let software make decisions on its own. Access permissions, audit logs, clear escalation rules, and human approval matter especially when a mistake could affect someone’s money or access to a financial service.
-
Agentic Commerce Brings AI into the Payment Flow
AI agents are beginning to move beyond product recommendations toward taking action on a user’s behalf. In agentic commerce, a customer might ask an assistant to find a suitable product, compare options, and complete a purchase within agreed limits. Payment providers will need ways to establish who authorized the transaction, what the agent was allowed to do, and how the purchase can be challenged if something goes wrong.
For fintech entrepreneurs, the opportunity may arrive first in structured business processes rather than everyday consumer shopping. Supplier payments and accounts payable already rely on invoices, approval rules, and known counterparties, which makes them natural candidates for carefully controlled automation. Products in this space will need to treat consent, spending limits, transaction identity, and dispute handling as core features not details to add later.
-
Regulated Stablecoins Enter a New Phase
Stablecoins are digital tokens designed to hold a steady value, usually by tracking a currency such as the US dollar. They can make sense for some digital-asset and payment workflows, particularly where businesses need to move value across systems or borders. But a token’s usefulness depends on more than its price peg: reserve quality, redemption rights, custody, issuer governance, and the legal framework all matter.
The GENIUS Act is scheduled to take effect on January 18, 2027, according to the regulatory snapshot used for this article. Businesses considering stablecoin features should examine which issuers and activities are permitted, how redemption works, and what anti-money-laundering, custody, and recordkeeping duties may apply to their role. The strongest business case will be specific—such as improving a settlement process—not simply the desire to add a crypto feature.
-
Tokenized Deposits Offer Another Route to Digital Settlement
Tokenized deposits represent bank deposits in digital-token form. They differ from stablecoins because they are structured as claims on a bank rather than tokens issued by a separate stablecoin provider. Depending on the system and legal arrangement, they may support transfers outside traditional banking hours and connect money movement with automated business processes.
Treasury teams and companies making frequent business payments are likely to be the most relevant audiences to watch. For fintech builders, the practical questions are whether customers need faster settlement, which banks and networks support the approach, and how the solution will connect with existing accounting and payment systems. Interoperability and access will determine whether tokenized deposits solve a real problem or remain a niche capability.
-
Instant Payments Raise the Bar for Money Movement
FedNow and The Clearing House’s RTP network give participating US financial institutions ways to send payments in near real time, around the clock. Faster transfers can improve use cases such as gig-worker payouts, insurance claims, supplier payments, payroll, and pay-by-bank checkout. In these settings, the timing of a payment can be part of the customer experience rather than a back-office detail.
The trade-off is that instant payments leave less time to catch a mistake or stop fraud. A product team needs to think through transaction limits, recipient verification, monitoring, exception handling, reconciliation, and support for disputed transfers. Before choosing an integration, identify the payment journeys where faster delivery would make a measurable difference and confirm what your banking or network partners can support.
-
Fintech Companies Consider Bank and Trust Charters
Some fintech businesses are exploring their own bank or trust charters instead of relying entirely on partner institutions. A charter can give a company more direct control over parts of its financial model, but it also brings substantial obligations around capital, governance, risk, compliance, and regulatory supervision.
It is not automatically the right next step for a growing fintech. The decision depends on the product, funding needs, customer base, economics, and the company’s ability to operate under ongoing oversight. For many businesses, a well-designed partnership may remain more practical. Founders should model both options and get qualified legal and regulatory advice before building their strategy around a charter.
-
Open Banking Depends on Trustworthy Data Access
Open banking lets consumers authorize financial-data sharing between banks and third-party services, often through APIs. That access supports account aggregation, personal financial management, lending decisions, and payment services. In the US, the direction and timing of Section 1033 implementation and whether data providers may charge for access remain important variables for product teams.
A fintech product that depends on account data should be built for customer control and changing technical conditions. That means clear consent, secure connections, a way to revoke access, careful data retention, and a plan for API outages or revised pricing. It is risky to base a business model on the assumption that data access will always be free or technically uniform across institutions.
-
AI-Enabled Fraud Makes Identity Harder to Prove
Fraudsters can use generative AI to create convincing messages, imitate voices, manipulate documents, and make synthetic identities look more credible. AI can also help financial companies identify suspicious activity, but no single model or identity check will catch every attack. Fraud prevention is becoming a layered process that combines identity, device, behavior, transaction context, and human review.
For a fintech product, the right controls depend on the risk of the action. A low-value login and a large transfer should not necessarily trigger the same checks. Multifactor authentication, step-up verification, transaction monitoring, risk-based limits, and a clear account-recovery process can work together to reduce exposure. Teams should also track false positives so legitimate customers are not repeatedly blocked by over-sensitive controls.
Building a Secure and Scalable Fintech Product?
From fraud prevention and payment integrations to AI-powered financial features, the right technology foundation can help turn your fintech idea into a reliable product.
- Cash-Flow Data Adds Context to Credit Decisions
Traditional credit scores remain important, but they do not tell the whole story for every borrower. Cash-flow underwriting looks at permitted bank-account or transaction data to understand income, spending, and repayment capacity. It can be useful for people with thin credit files and small businesses whose financial picture is not well represented by a conventional score alone.
More data does not guarantee better lending decisions. Founders building underwriting tools need reliable data, meaningful borrower consent, fair-lending tests, privacy safeguards, and a way to explain how decisions are reached. A sensible first step is to compare cash-flow signals with actual repayment outcomes and check whether they improve decisions without creating unacceptable bias or risk.
-
Embedded Finance Becomes More Specific to the Industry
Embedded finance places services such as payments, lending, cards, or insurance inside software people already use. A restaurant platform might offer payment processing; a field-service system could help contractors collect invoices; a business-management tool might provide access to working capital. The service is most compelling when it fits naturally into an existing task.
For entrepreneurs, this makes industry knowledge a real advantage. A company that understands a customer’s daily workflow may be better placed to identify the right financial feature than a general-purpose app provider. Start with one clear use case and make sure the economics, partner arrangements, and support model work before expanding into more complex services such as credit or insurance.
-
Banking-as-a-Service Puts Operations under Greater Scrutiny
Banking-as-a-Service (BaaS) allows fintechs to offer products such as accounts, cards, and payments through relationships with regulated banks. The model can help a company reach market without becoming a bank itself, but it does not remove the need for dependable records, clear responsibilities, and careful partner oversight.
The Synapse collapse drew attention to what can happen when records and responsibilities are fragmented across providers. A fintech considering BaaS should be able to explain how customer balances are tracked, how records reconcile with partner institutions, who handles complaints, and what happens if a provider relationship ends. A clean ledger and documented operating procedures are essential parts of a financial product.
-
RegTech Is Becoming Part of the Product Itself
RegTech software helps financial businesses manage identity checks, transaction monitoring, regulatory reporting, audit evidence, and policy changes. As products grow and requirements multiply, spreadsheets and manual reviews can become difficult to maintain. Well-designed automation can help teams organize evidence, prioritize alerts, and keep a clearer record of why an action was taken.
Compliance should be considered during product design, not bolted on just before launch. Consent records, access controls, audit logs, data lineage, and review workflows are easier to build in early than to retrofit later. The exact requirements will depend on the product and the jurisdictions in which it operates, so software should support not replace advice from qualified compliance and legal professionals.
-
Digital Government Payments Highlight Access and Usability
The move away from paper checks toward electronic government payments puts more emphasis on accessible accounts, payment cards, digital wallets, and simple account-opening journeys. The transition can be inconvenient for people who lack a bank account, have difficulty completing identity checks, or need help understanding fees and payment options.
There may be opportunities for fintech products that make receiving and managing funds easier, but trust and accessibility have to be part of the design. Clear instructions, transparent fees, inclusive user experiences, and responsive support can matter as much as the underlying payment technology. Any product connected to a government program must also meet that program’s specific requirements.
-
ISO 20022 Makes Payment Information More Valuable
ISO 20022 is a financial messaging standard that carries structured information with payment instructions. That information can help businesses match incoming payments to invoices, automate reconciliation, improve reporting, and reduce manual investigation. The value is not just in sending a payment; it is in preserving the details that explain what the payment is for.
Fintech platforms can create value by making sure those details survive as information passes between banks, payment providers, and business systems. Treasury, accounts-receivable, and reconciliation tools are natural areas to explore. Product teams should map which fields each integration supports, validate the data, and make missing or inconsistent information visible instead of quietly discarding it.
-
Core Modernization Creates Room for Focused Fintech Infrastructure
Financial institutions often need to improve old technology without taking on the risk of replacing every system at once. A staged approach can add modern APIs, customer-facing experiences, analytics, or workflow tools alongside a legacy core. This can make modernization more manageable while allowing institutions to address the most urgent limitations first.
For fintech companies selling to banks, a focused solution may be easier to evaluate than a pitch to replace an entire platform. Buyers will still expect strong security, integration support, resilience, documentation, and vendor-risk reviews. Founders should understand the operational problem they are solving and be realistic about the time required to sell into regulated institutions.
-
Post-Quantum Cryptography Belongs on the Security Roadmap
Post-quantum cryptography uses cryptographic methods designed to withstand attacks from future quantum computers. The timing of practical quantum threats is uncertain, but financial data may need to remain confidential for many years. That makes it worth understanding where cryptography is used and how difficult it would be to replace vulnerable components in the future.
Early preparation does not mean rushing into an untested migration. It means keeping an inventory of cryptographic dependencies, following recognized standards, asking vendors about their roadmaps, and designing systems that can adapt as standards and recommendations evolve. Products with long-lived sensitive data or complex vendor chains have particular reason to start documenting these dependencies.
-
AI Financial Coaches Become More Personal
AI-powered financial guidance can help people understand spending, plan for bills, set savings goals, and make sense of their financial patterns. Instead of waiting for a customer to ask a question, an app may offer a timely reminder when a bill is due or spending is moving away from a stated goal.
Useful guidance needs context and restraint. A stream of generic alerts will quickly be ignored, while inaccurate advice can undermine trust. Fintech teams should let users control notifications, explain why a suggestion appeared, protect the data behind it, and be clear about the limits of automated guidance. A focused audience—such as freelancers with irregular income—may benefit more from a tailored tool than from a chatbot that tries to do everything.
How to Prioritize the Right Fintech Trends for Your Startup
A fintech trend may seem exciting, but it is not always the right investment for your business. Start by identifying the problems your customers face and the areas where your business needs improvement. For example, instant payments may help address slow payouts, while AI-assisted workflows can reduce the time spent reviewing documents.
Before investing in a new trend, consider the following factors:
- Customer Demand: Identify whether the trend solves a genuine customer problem or improves the user experience.
- Business Impact: Estimate its potential effect on revenue, customer retention, processing costs, and fraud prevention.
- Technical Readiness: Evaluate data availability, banking partnerships, vendor dependencies, security requirements, and the resources needed for implementation.
- Regulatory Compliance: Ensure the solution meets applicable financial regulations, privacy requirements, and security standards.
- Strategic Fit: Prioritize initiatives that align with your startup’s long-term goals and available resources.
Finally, test the most critical assumptions before committing significant resources. Use customer interviews, prototypes, or controlled pilot projects to validate demand and assess real-world performance. Focus on trends that deliver measurable business value, meet regulatory requirements, and can be implemented effectively.
How Code Brew Labs Helps Build Fintech Software
Code Brew Labs helps startups, financial institutions, and growing businesses turn financial technology ideas into scalable digital products. As a fintech software development company, Code Brew Labs focuses on building solutions around specific business requirements, customer needs, and operational goals. From developing a new financial product to modernizing an existing platform, the team combines product strategy, UI/UX design, software engineering, and third-party integrations to support the development journey.
Its fintech development expertise can support solutions such as:
-
- Digital Banking Solutions: Applications that enable users to manage accounts, view transactions, transfer funds, and access digital financial services.
- Digital Wallet Development: Secure wallet experiences for storing balances, managing transactions, and supporting digital payments.
- Payment and Money Transfer Platforms: Solutions designed to streamline payment processing, fund transfers, and transaction management.
- Lending and Loan Management Software: Digital platforms for loan applications, borrower onboarding, repayment tracking, and lending workflows.
- Investment and Wealth Management Applications: Tools that help users monitor portfolios, access financial information, and manage investments.
- Embedded Finance Solutions: Financial capabilities integrated into existing applications and business platforms.
- AI-Powered Fintech Solutions: AI-enabled workflows for document processing, customer support, data analysis, and operational efficiency.
Have a fintech product idea to build or improve?
Consult with our team about product strategy, fintech software development, integrations, and a practical path to launch.
Conclusion
The fintech trends to watch in 2027 are not all at the same stage. Some, such as instant payments and embedded finance, can address immediate customer needs. Others, including agent-led transactions, stablecoin products, and post-quantum preparation, require careful attention to permissions, infrastructure, security, or evolving rules. The right priorities will look different for a payments startup, a lender, and a software company serving small businesses.
Rather than trying to adopt every new technology, choose the few developments that solve a real problem for your customers. Validate the business case, account for compliance and security early, and test the riskiest assumptions before scaling. That is how a fintech trend becomes a useful product decision instead of another item on a roadmap.
Frequently Asked Questions
-
Which fintech trends are realistic for an early-stage startup to test?
It depends on the customer problem and the team’s resources. A focused embedded-payment feature, a better onboarding flow, or an AI tool for a clearly defined internal task may be easier to validate than a complex stablecoin or charter-related project. Start with a prototype or limited pilot and confirm the relevant partner, security, and regulatory requirements before handling live financial activity.
-
How can founders tell whether an AI feature is worth building?
Choose a recurring task with a measurable cost or customer impact, then compare the current process with a controlled AI-assisted version. Track time saved, error rates, employee corrections, customer outcomes, and the cost of human review. If the feature adds complexity without improving those measures, it may not be ready for production.
-
What should a fintech MVP include before it handles real transactions?
Beyond the core user journey, teams need to plan for authentication, permissions, error states, transaction records, monitoring, customer support, data protection, and recovery when a payment or integration fails. The exact requirements depend on the product and partners. Security and compliance reviews should happen before launch, not after real customers are using the system.
-
Does working with a bank or BaaS provider mean a fintech has no compliance obligations?
No. Responsibilities depend on the product, contracts, jurisdiction, and activities each company performs. A partner may provide regulated services, but the fintech still needs to understand its obligations around disclosures, data handling, customer complaints, security, records, and oversight. Founders should obtain advice specific to their intended model.
-
What affects the cost of developing fintech software?
The main factors include product complexity, platforms, integrations, security requirements, data flows, testing, regulatory scope, and ongoing support. A tightly scoped MVP will generally cost less than a platform involving multiple user roles, payment rails, lending workflows, and third-party services. Discovery helps establish a realistic scope before a full estimate is prepared.
-
How long does it take to launch a fintech MVP?
There is no reliable timeline that fits every fintech product. A prototype with limited functionality is very different from a production platform handling sensitive data or real payments. The schedule depends on scope, team capacity, integrations, testing, partner reviews, and any required approvals. Plan around milestones and dependencies rather than relying on a generic promise.
-
What should a company look for in a fintech software development partner?
Look for experience with comparable product workflows, integration-heavy systems, security-minded development, clear delivery practices, and support after launch. Ask who owns the code and intellectual property, how changes are managed, how risks are communicated, and how the team will coordinate with your legal, compliance, and financial partners. A good partner should be able to explain trade-offs, not just agree to every feature request.
Let's Convert Your Business Idea Into Success!
Free Consultation from Top Industry Experts
Let’s Build Your Dream App!
Share article on :


Ready To Fuel Your Vision With AI-Powered Innovation?




Level- 18, Dubai World Trade Centre Tower, Sheikh Rashid Tower, Sheikh Zayed Rd, Dubai, UAE
business@code-brew.com +971-55-645-7972
Plot no I - 36, Sector 83 Alpha, Mohali SAS Nagar 140308
business@code-brew.com +91-771-976-8427
Al Akaria 2, 6926 Olaya Street, RHOA2566, Riyadh, Saudi Arabia.
business@code-brew.com
Av. Miguel Hidalgo y Costilla 1995, Arcos Vallarta, 44600 Guadalajara, Mexico
business@code-brew.com +1(213)2614953
4231 Balboa Ave #512 San Diego, CA 92117 United States
business@code-brew.com +1(213)2614953
2nd floor, College House, 17 King Edwards Rd, London HA4 7AE, UK
business@code-brew.com +44 (20) 82644493
Partner With Experts Who Leverage AI & Tech To Transform Ideas Into Market-Leading Solutions.
Wait! Looking for Right Technology Partner For Your Business Growth?
It's Time To Convert Your Business Idea Into Success!
Get Free Consultation From Top Industry Experts:
I would like to keep it to myself